VAT Return Changes: Why [32a], [32b] and [34a] Matter for Revenue Classification
Introduction
Not every transaction or receipt that does not give rise to output VAT should be treated in the same way.
A business may receive compensation or settlement amounts, collect or pay amounts on behalf of another party, undertake real-estate transactions involving deductible land value, or provide services in cross-border arrangements.
This distinction matters because an incorrect VAT classification can lead to an inaccurate VAT return, inconsistencies between contracts, invoices and accounting records, additional review or adjustment work, and potential tax-compliance exposure. It may also affect the assessment of shared input VAT.
From 1 July 2026, the revised Form 01/GTGT under Circular No. 89/2026/TT-BTC introduces new Items [32b] and [34a] and revises the presentation of [32a]. This makes the distinction between these categories more explicit when businesses prepare their VAT returns.
The revised form applies from the July 2026 monthly period or the third quarter of 2026. Returns for tax periods before 1 July 2026 continue to use the previously applicable forms.
This article explains what has changed, why it matters for businesses, and what should be reviewed before filing the revised VAT return.
Article Outline
- I. What Has Changed in Form 01/GTGT?
- II. Understanding the Key Differences
- PCA Note
I. What Has Changed in Form 01/GTGT?
The revised Form 01/GTGT introduces two new reporting items, [32b] and [34a], alongside the existing Item [32a].
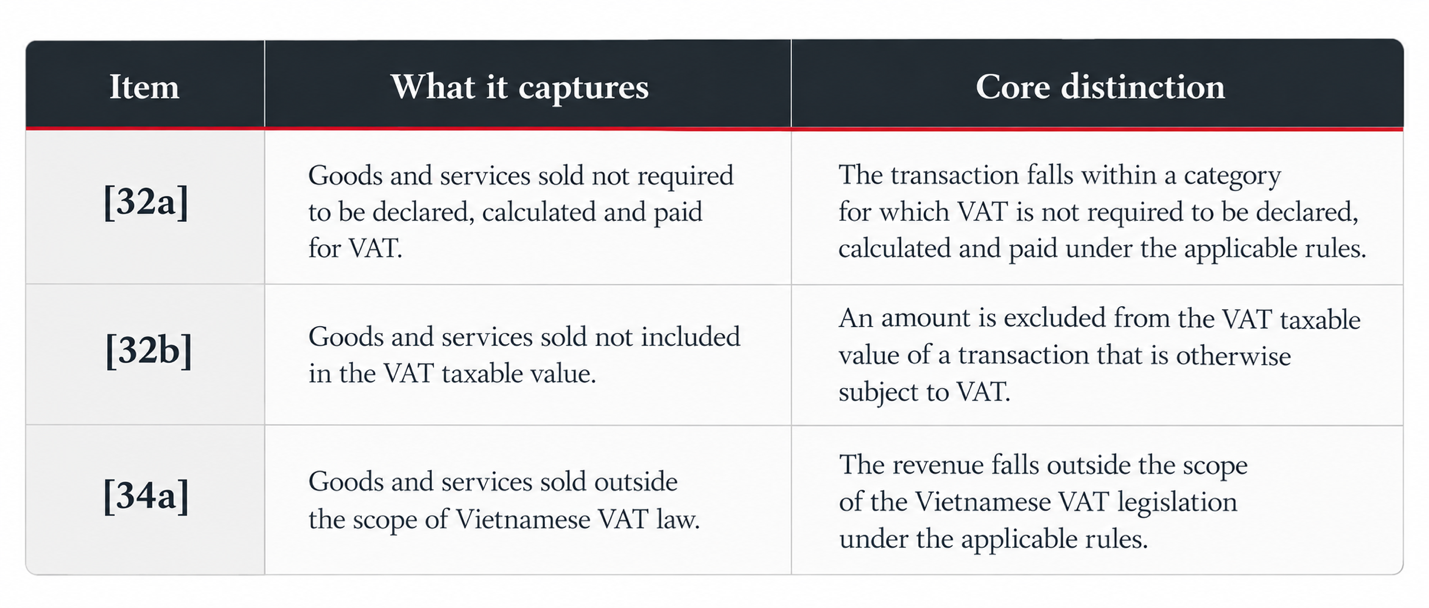
Table 1: Key distinctions between VAT return items [32a], [32b] and [34a].
Note: An amount excluded from the VAT taxable value is not automatically reportable in [32b]; the applicable reporting and invoice treatment must also be checked.
The revised form therefore distinguishes more clearly between transactions for which VAT is not required to be declared, calculated and paid, amounts excluded from the VAT taxable value, and activities outside the scope of Vietnamese VAT law.
For businesses moving from the previous VAT return form to the revised Form 01/GTGT, existing accounting or tax-code mapping should therefore be reviewed rather than carried forward automatically.
II. Understanding the Key Differences
Figure 1: Conceptual illustration of VAT return items [32b] and [34a].
[32a] – Goods and services sold not required to be declared, calculated and paid for VAT
Item [32a] is used for goods and services that fall within cases where VAT is not required to be declared, calculated and paid under the applicable VAT rules.
One current example is the sale, between qualifying businesses or cooperatives, of certain agricultural, forestry, livestock and fishery products that have not been processed into other products or have only undergone ordinary preliminary processing, subject to the conditions prescribed by law.
Other transactions should be assessed against the specific legal provision applicable to their facts before being reported under [32a].
[32b] – Goods and services sold not included in the VAT taxable value
Item [32b] is used to report an amount that the law allows to be excluded when determining the VAT taxable value of a transaction that is otherwise subject to VAT.
Typical situations may involve amounts that VAT law excludes from the taxable value, such as the deductible land value in qualifying real-estate transactions or certain collection-on-behalf amounts. However, whether such an amount is actually reported in [32b] must also be checked against the reporting instructions for Form 01/GTGT, including the applicable e-invoice treatment.
The key point is that [32b] concerns an amount excluded from the VAT taxable value. It does not mean that the entire transaction is outside the VAT system.
[34a] – Goods and services sold outside the scope of Vietnamese VAT legislation
Item [34a] is used to report revenue from goods and services falling outside the scope of Vietnamese VAT legislation in accordance with Article 40(2) of Decree No. 181/2025/NĐ-CP and the relevant implementing guidance.
For cross-border services, the analysis should consider the actual place of performance, use or consumption of the service and the applicable VAT rules. The mere involvement of a foreign customer, supplier or overseas payment does not, by itself, determine that a transaction belongs in [34a].
PCA Note
The introduction of [32b] and [34a] highlights an important practical point for accounting teams: the VAT return should be the result of a correct transaction assessment, rather than the starting point for classification.
At PCA, we approach VAT reporting by connecting the underlying transaction, contractual and accounting records with the applicable VAT treatment. This is particularly important for unusual, material or cross-border transactions, where the appropriate classification may not be apparent from the accounting description alone.
For further information and practical advice on the revised VAT return or the appropriate treatment of a specific transaction, clients may contact the PCA Team to discuss the relevant facts and supporting documents. Clients may also request PCA’s practical recommendations on this topic.
Email: info@pca-cs.com
Hotline: +84 (0) 909 090 415 | +84 (0) 909 091 141
Author: Chief Financial Officer, Mr. Nguyen Quoc Tu
Legal Basis
Official Circular No. 89/2026/TT-BTC: Article 100(1) and Form 01/GTGT in Appendix I.
Tags: #VAT2026 #VietnamVAT #VATReturn #VATCompliance #VietnamTax #VietnamTaxUpdate #VATFiling #Circular892026 #VATReturn2026 #TaxCompliance #VietnamBusiness