Managing Asset Leasing Tax Compliance Under Vietnam’s 2026 Regulations
Article Outline
- Introduction & Practical Context
- Asset Leasing Tax from 2026: Policy Adjustments and Stronger Enforcement Trends
- Adjustment of Taxable Revenue Thresholds under the New Regulations
- Tax Declaration Obligations Are Independent of Tax Payable
- Trend toward Stronger Tax Administration through Data Integration
- Risks of Tax Reassessment and Penalties in Cases of Non-Compliance
- PCA Note
I. Introduction & Practical Context
From 2026, Vietnam’s asset leasing tax framework will introduce important adjustments in taxable thresholds and tax administration methods.
However, before analyzing the regulatory changes, it is important to clarify a practical reality that many businesses are currently facing: in practice, landlords often shift the tax payment responsibility to tenants.
Under Vietnamese tax law, rental income tax (VAT and PIT) is legally the responsibility of the individual landlord, as the income-earning party.
Nevertheless, in B2B lease arrangements, it is frequently the tenant company that ultimately bears the tax burden, primarily because:
- The tenant requires proper tax declarations and supporting documents in order to ensure that rental expenses are deductible for Corporate Income Tax purposes; and
- Landlords often condition the lease on the tenant covering the rental tax amount.
As a result, although the legal liability belongs to the landlord, the economic burden is commonly transferred to the tenant.
Under the previous framework, the taxable threshold was VND 100 million per year. In most commercial lease arrangements, annual rental value typically exceeded this amount (for example, VND 15–20 million per month already surpasses the threshold).
Accordingly, tenants could easily determine that the contract fell within the taxable scope and, in practice, were willing to bear the rental tax in exchange for proper documentation and expense deductibility.
However, from 2026 onward, with the taxable threshold increasing to VND 500 million per year, this long-standing practice may create new ambiguities and risks — particularly where landlords have multiple lease contracts and total rental income aggregation determines tax liability.
In such cases, a tenant’s individual lease may be below VND 500 million annually, yet the landlord’s total rental income from multiple properties may exceed the threshold. This creates uncertainty as to whether tax arises, and if so, who should bear it.
Both individual lessors and business lessees should therefore reassess their tax positions and contractual structures to avoid reassessments, penalties, and unintended tax burden shifting under the new administration framework.
II. Asset Leasing Tax from 2026: Policy Adjustments and Stronger Enforcement Trends
From 2026, Vietnam’s legal framework governing asset leasing will undergo significant changes in both tax policy and tax administration. While no new taxes are introduced, the revised regulations reflect a clear direction toward standardizing tax obligations for income derived from asset leasing, particularly for individual lessors.
These changes should be viewed within the broader context of tax administration reform, where data collection, data integration, and cross-checking mechanisms play an increasingly central role.
Key Takeaway: Transparency and data-based supervision will be central to how leasing income is monitored.
III. Adjustment of Taxable Revenue Thresholds under the New Regulations
Under Personal Income Tax Law No. 109/2025/QH15, income earned by individuals from asset leasing is subject to Personal Income Tax (PIT) only if annual revenue exceeds VND 500 million. The applicable PIT rate is 5% calculated on total leasing revenue once the threshold is exceeded.
At the same time, Value Added Tax Law No. 48/2024/QH15 provides that households and individuals engaged in business activities – including asset leasing – are not subject to VAT if annual revenue does not exceed VND 500 million. Once this threshold is exceeded, VAT is calculated using the direct method on revenue at a rate of 5%.
Raising the revenue threshold is considered a policy adjustment that more clearly distinguishes between small-scale leasing activities and leasing activities that generate stable and significant income.
Key Takeaway: PIT and VAT apply only when annual leasing revenue exceeds VND 500 million, clearly separating small-scale leasing from income-generating activities. However, once the threshold is exceeded, VAT applies at 5%, while PIT at 5% applies only to the portion of revenue exceeding VND 500 million.
IV. Tax Declaration Obligations Are Independent of Tax Payable
An important point to note is that the revenue threshold for tax liability does not mean exemption from tax declaration obligations. Under current tax administration rules, individuals who generate income from asset leasing are still required to declare their revenue to the tax authorities, even if their revenue does not exceed the threshold and no tax is payable.
Tax declarations serve as the basis for tax authorities to monitor, manage, and cross-check information across tax periods. As Vietnam’s tax system becomes increasingly data-driven, declaration obligations form the foundation of overall tax compliance.
Key Takeaway: Not exceeding the revenue threshold does not remove the obligation to declare leasing income. Tax declarations remain mandatory and form the foundation for data monitoring by tax authorities.
V. Trend toward Stronger Tax Administration through Data Integration
Alongside policy adjustments, tax authorities are gradually strengthening their ability to cross-check and analyze data from multiple sources. These include tax declarations, banking payment data, lease contracts, and rental expenses declared by lessees.
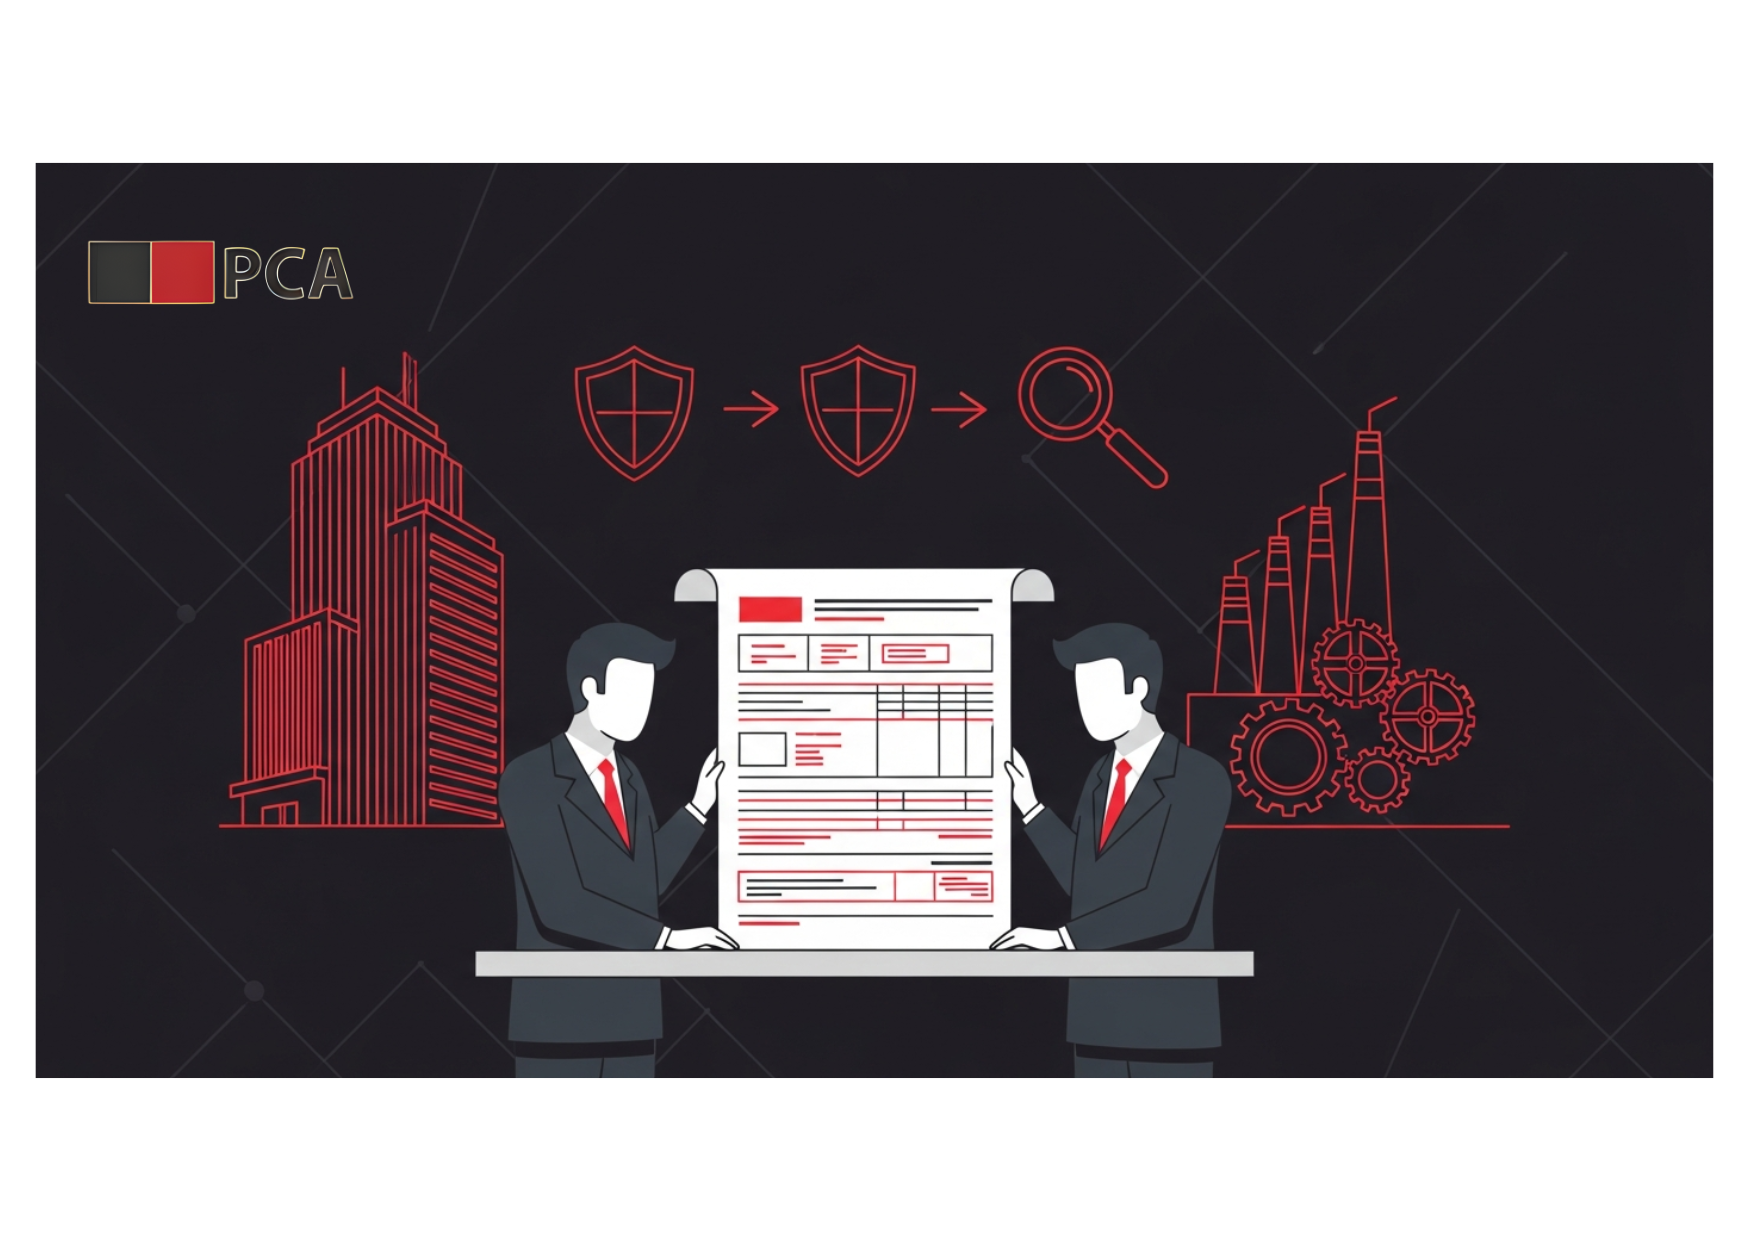
In practice, an individual’s rental income may be identified indirectly through related parties, especially when the lessee is a business entity. This significantly reduces the possibility of concealing leasing income over an extended period without detection.
This trend shows that enforcement focus is not only on issuing new regulations, but also on strengthening implementation and control capabilities.
Key Takeaway: Tax authorities can increasingly detect leasing income through data cross-checking from multiple sources. Concealing rental income is becoming significantly more difficult, especially when lessees are businesses.
VI. Risks of Tax Reassessment and Penalties in Cases of Non-Compliance
If tax authorities determine that an individual has earned rental income but failed to declare it or declared it incorrectly, tax obligations may be reassessed retroactively for prior periods. Depending on the nature and severity of the violation, lessors may face back taxes for VAT and PIT, late payment interest, and administrative tax penalties.
In a data-driven tax environment, these risks are increasingly real and may arise even in cases that previously attracted limited scrutiny.
PCA Note
The 2026 adjustment to Vietnam’s asset leasing tax framework represents more than a change in threshold; it reflects a broader shift toward aggregated income assessment and stronger data-driven supervision.
For businesses, particularly those leasing assets from individuals, the key issue is no longer whether tax applies in principle, but how tax responsibility is structured and allocated in practice.
Clear contractual allocation, proper documentation, and timely review are now essential elements of risk management — not merely compliance formalities. Taking proactive steps before the new framework becomes fully operational will help reduce ambiguity, prevent unintended tax burden shifting, and protect both accounting integrity and commercial relationships.
A timely consultation with PCA could assist align leasing structures and documentation to maintain cost deductibility and compliance in a more transparent regulatory environment.
Contact us now!
Email: info@pca-cs.com
Hotline: +84 (0) 90909 0415 | +84 (0) 909091141
Author: Chief Financial Officer, Mr. Nguyen Quoc Tu.