WEEKLY TRANSACTION INTELLIGENCE | SOUTHEAST ASIA
PCA M&A Briefing
Buying an operating business in Southeast Asia: what comes with the deal?
For business owners considering a sale, companies expanding into Southeast Asia and investors assessing acquisitions. This edition looks at a Vietnamese logistics acquisition, a planned Thai petrochemical combination and an Indonesian joint-venture buyout. Each shows why the value of a deal depends on what the buyer can operate after closing.
Focus of this edition. What the buyer can actually operate, finance and retain after closing — and which cash flows still depend on development, licences, approvals or additional capital.
THIS WEEK AT A GLANCE
CTP agrees terms for a US$500 million logistics platform
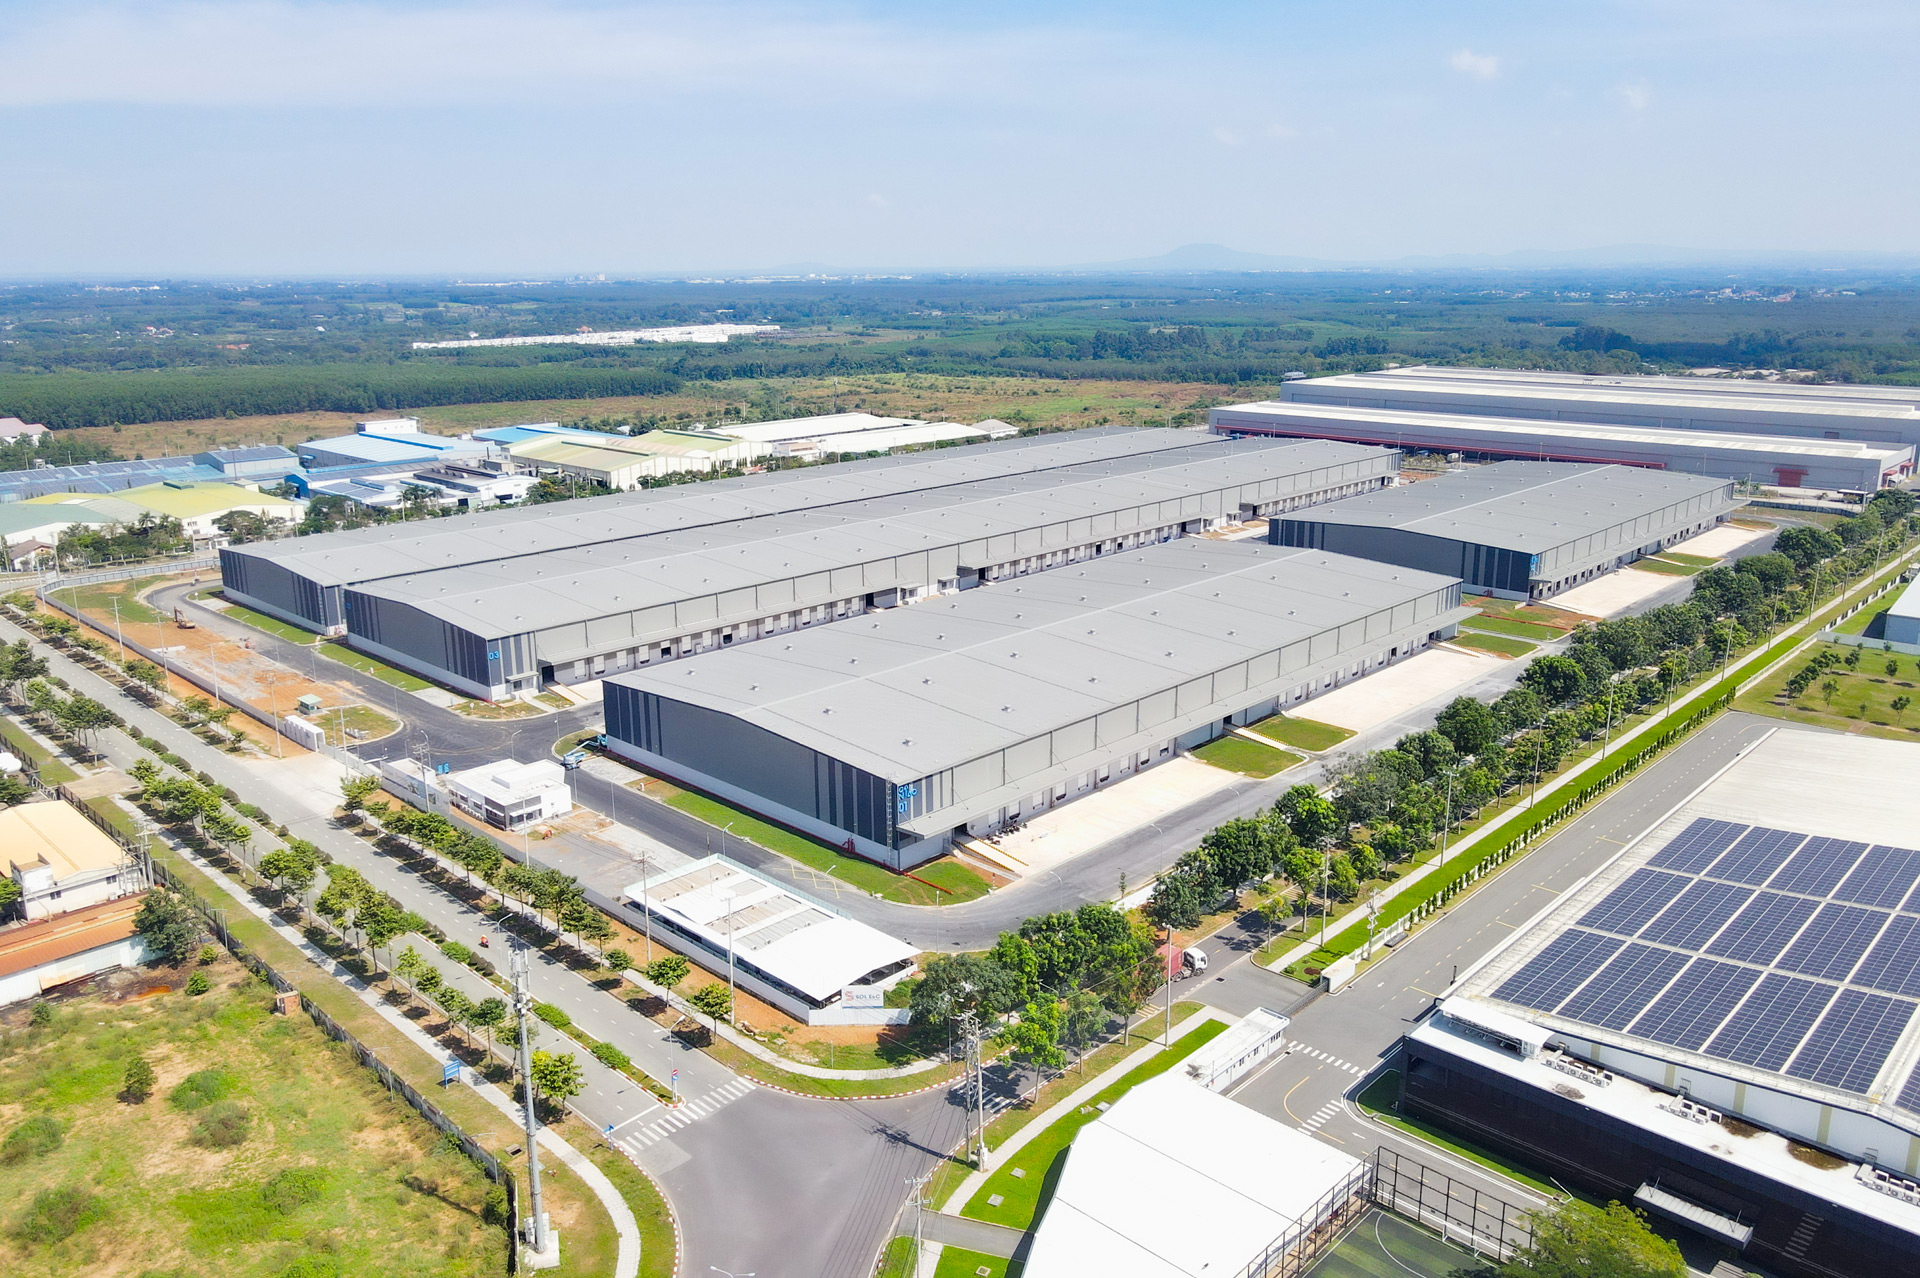
On 9 November, Netherlands-based CTP said it had agreed terms to buy the entire Vietnamese portfolio and operating platform of Ares Management-owned South-East Asia Logistics Partners for approximately US$500 million. The proposed acquisition covers seven existing properties with 504,000 m² of net lettable area and six development sites. Closing is subject to agreed conditions, including applicable regulatory approvals.
PCA'S PERSPECTIVE
For buyers of industrial property, separate the cash flow from leased buildings from the return expected on sites still to be developed. Test the remaining capital expenditure, the availability of utilities, and what existing leases and site rights allow before assigning value to future capacity.
PTT Global Chemical and SCG Chemicals advance a combination
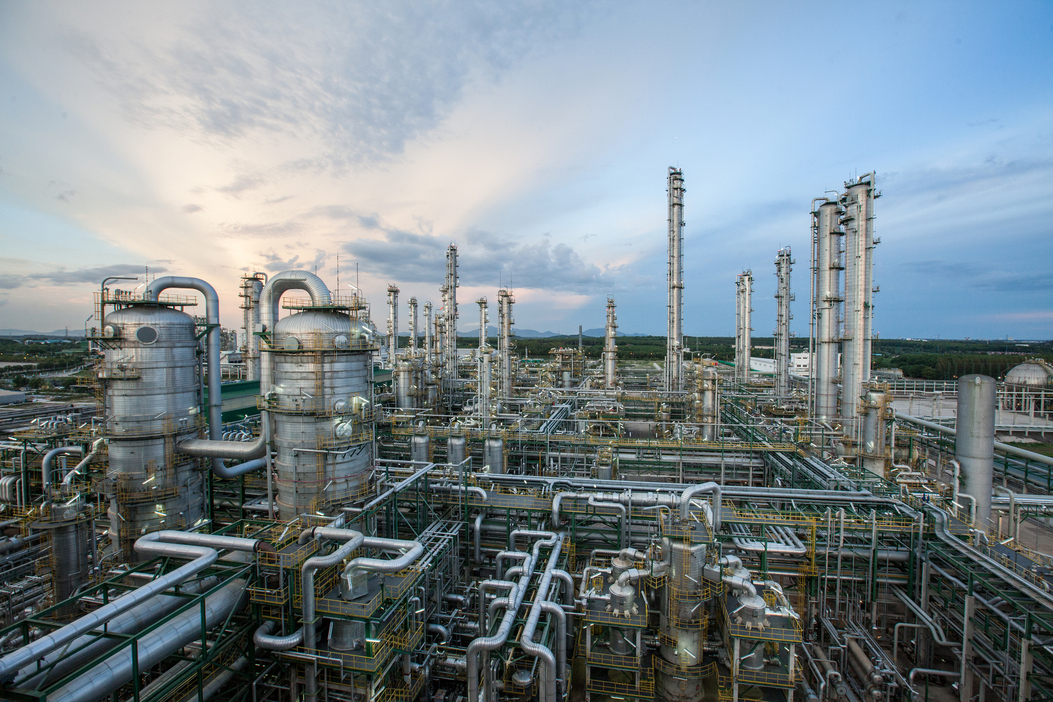
On 18 November, PTT Global Chemical disclosed its independent financial adviser’s opinion and the availability of its shareholder-meeting notice. On 19 November, SCG disclosed a revised information memorandum. The proposed Thai olefins and polyolefins combination would give PTT Global Chemical 56% and SCG Chemicals 44%, through a share swap with no cash consideration. It remains subject to shareholder and regulatory approvals and other conditions; the companies originally targeted establishment in the second half of 2027.
Additional sources: SCG revised information memorandum, 19 November 2026 | PTTGC transaction structure
PCA'S PERSPECTIVE
A share swap still leaves a valuation question: do the percentages reflect the assets, debt and obligations each party brings? A buyer or joint-venture partner should test the exchange ratio under different margin assumptions and agree who approves capital spending, guarantees and related-party supply contracts.
AKR acquires BP’s remaining stake but retains its brand licence
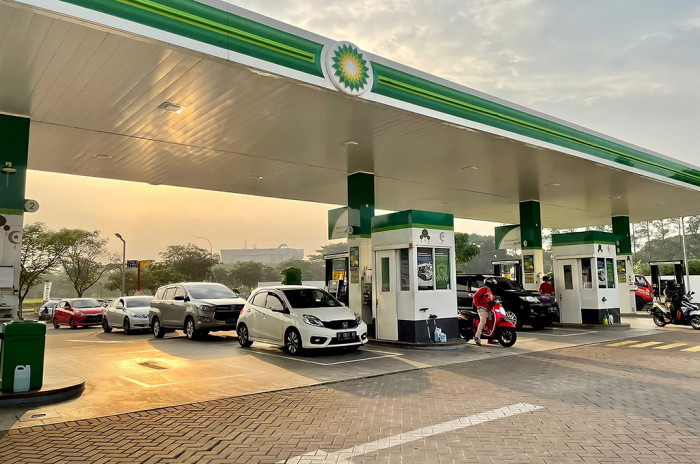
In a response to the Indonesia Stock Exchange made public on 20 November, AKR Corporindo clarified the effect of its completed buyout of BP Global Investments’ 49.9% stake in PT Aneka Petroindo Raya. The US$14.22 million transaction took effect on 6 November, increasing the AKR group’s ownership from 50.1% to 100%. AKR said the service stations would continue using the BP brand under the existing trademark licence.
Additional sources: Independent coverage (backup)
PCA'S PERSPECTIVE
Share ownership and brand ownership are separate. When a departing partner owns the brand, check the licence term, renewal and termination rights before valuing customer retention. Price the cost of rebranding if the licence ends.
Financing and market signals
These developments provide useful context for capital availability and investment activity, but they should not be read as completed acquisitions or guaranteed demand.
Vietnam | US$730m | Financing package for VPBank
IFC and Sumitomo Mitsui Banking Corporation co-arranged a US$730 million financing package for VPBank, announced on 10 November. IFC says it is intended to expand longer-term lending to SMEs. The package finances the bank; it is not a commitment to any individual borrower. Compare tenor, collateral and currency exposure against your own cash flows before budgeting for debt.
Philippines | PHP 166.03bn | Approved foreign investment commitments · Q3 2026
The Philippine Statistics Authority reported on 12 November that approved foreign investment commitments reached PHP 166.03 billion in Q3 2026, up 125.3% year on year. Manufacturing accounted for PHP 86.16 billion, or 51.9%. These figures measure commitments approved by investment promotion agencies, not capital already spent or demand secured by suppliers.
A question to ask before agreeing the price
Which cash flows can you operate and finance on day one, and which depend on a new lease, licence, permit or capital contribution? Put those dependencies in the deal timetable and test their effect on price, working capital and local tax costs before committing.
- 01Separate operating cash flowDistinguish earnings from assets already operating from returns that still depend on development or additional capital.
- 02Identify non-transferable rightsMap licences, brands, permits, leases and approvals that may need consent, renewal or replacement after closing.
- 03Test financing against realityModel debt, working capital, currency exposure and local tax costs using the buyer's actual post-closing cash flows.
PCA supports businesses assessing acquisitions, disposals, investment structures and related legal, financial and tax matters in Southeast Asia.
Where the relevant assistance is included in an existing PCA engagement, it is provided within the agreed scope. For additional support, or clarification of your current coverage, please contact your PCA adviser.
PCA LEADERSHIP
Mr. Lê N. Bảo
Chief Executive Officer
PCA Group
Ms. Phan Thị Tường Vy
Chief Operating Officer
PCA Group